Medical Council · NMBI · Dental Council · Pharmaceutical Society of Ireland · CORU · Complaint or fitness to practise inquiry
Financial Integrity for Healthcare Professionals facing a complaint to your regulator or a fitness to practise inquiry about fees, billing, claims or a financial interest
A complaint, an audit or an investigation about money?
- Claims — a claim for a service not provided, an inflated code or a duplicate claim
- Fees — a charge not explained in advance, or fees applied unevenly between patients
- Conflicts of interest — a referral to a service you own, or a product you sell, not declared
- Gifts and sponsorship — hospitality, gifts or incentives linked to prescribing or referrals
- Public and private — double charging, or private patients prioritised for financial reasons
- Expenses — expense claims or allowances estimated rather than documented
- Delegated billing — claims submitted in your name by staff or a third party, without checks
- Any other concern — about your honesty or judgement in a financial matter
Facing a complaint or a fitness to practise inquiry about fees, billing, claims or a financial interest — before the Medical Council, NMBI, the Dental Council, the Pharmaceutical Society of Ireland or CORU?
This course is for a healthcare professional whose billing, claims, fees or financial relationships are the subject of a complaint, an audit or a fitness to practise inquiry. This course helps you remediate — and show the remediation, with a dated certificate for your written response, your reflection, an undertaking or an inquiry.
| Courses | Price per course | You save |
|---|---|---|
| 1 | €100 | No saving |
| 2 | €88 | €25 |
| 3 | €83 | €50 |
| 5 | €80 | €100 |
| 10 | €70 | €300 |
Add courses. The saving is applied in the basket.
Immediate access · certificate on completion · twelve months' access
- 2 CPD hours
- Self-paced
- Written for Ireland
- CPD certificate
- From €70 a course (Bulk Buy of 10)
 Dr Shehzad IqbalFounder, course author and facilitatorMBBS, MRCS, MRCGP
 Dr Mo MirzaCourse facilitatorMedically trained, UCL London
 Ludmila UpenieceBusiness development and supportPsychology, UEL London
At a glance
- Who it is for
- Any healthcare professional in Ireland facing a complaint, an audit, an employer process or a fitness to practise inquiry about billing, claims, fees, expenses, conflicts of interest, gifts, sponsorship or financially influenced decisions
- Regulator covered
- Applies to practitioners registered with the Medical Council, the Nursing and Midwifery Board of Ireland (NMBI), the Dental Council, the Pharmaceutical Society of Ireland (PSI) or CORU
- Length
- 10 sections, 83 lessons, 2 CPD hours
- Format
- Self-paced, online, immediate access, twelve months from purchase
- Certificate
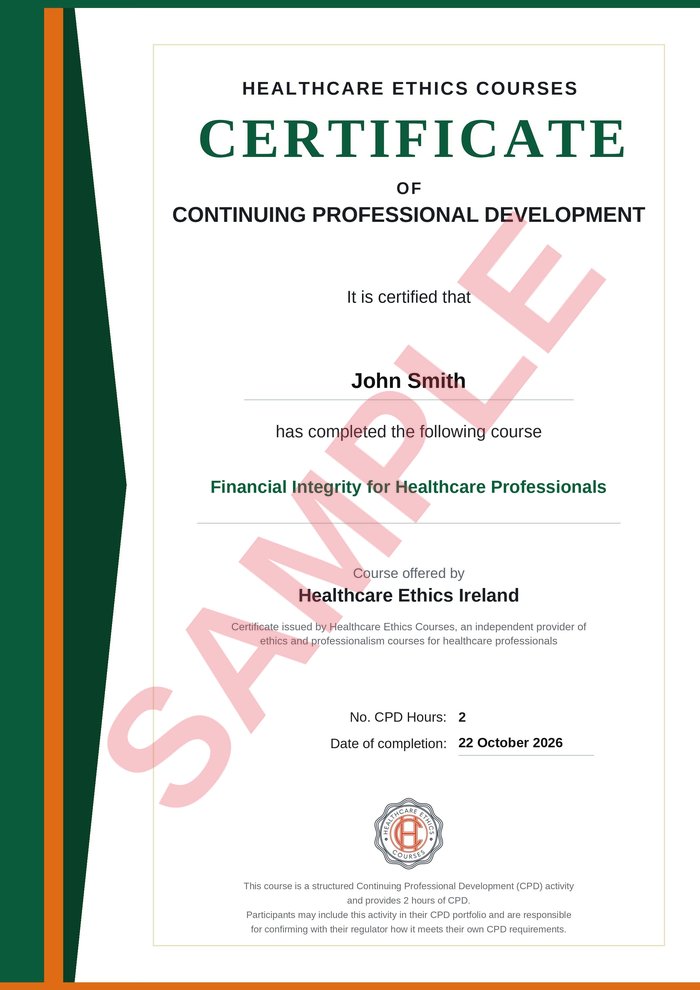
- Certificate issued by Healthcare Ethics Courses on completion, dated, with the course title and 2 CPD hours
- Price
- €100 · from €70 a course (Bulk Buy of 10)
Certificate issued by Healthcare Ethics CoursesRemediation courses for regulatory processes.
The certificate you will receive
How healthcare professionals use it
- With a written response to your regulator or its preliminary committee, alongside a reflection
- When an undertaking or a consent is discussed, or in your evidence to an inquiry committee
- As a dated record of remediation for the regulator when sanction is considered
Who this course is for
After an audit found discrepancies
An audit of claims, expenses or billing has found errors over months, and the question now is whether they were careless or dishonest. Section 3 covers the billing and claim errors that attract scrutiny, patterns and audit trails, and Section 7 audits, reviews and information requests.
Facing a complaint to your regulator
The Medical Council, NMBI, the Dental Council, the PSI or CORU has written to tell you of a complaint. Your first written reply is where your honesty in financial matters is read first. Section 7 sets out what a response should include.
Facing parallel employer and regulatory processes
An employer’s disciplinary or conduct review and a regulator’s process can run side by side, and what you say in one is compared with the other. Section 7 covers parallel processes and keeping explanations consistent and evidence-based.
Questioned about a conflict of interest
A referral pattern, an ownership interest, an advisory role or a sponsored event has been questioned. Sections 4 to 6 cover conflicts of interest, gifts and industry relationships, and prescribing and referral decisions under financial influence.
Facing an allegation of professional misconduct
Claims for work not done, overcharging, an undisclosed interest: financial matters go to probity. Section 2 covers honesty in financial dealings, and Section 8 compares weak and strong responses in financial investigations.
Facing a fitness to practise inquiry
The complaint has gone to a Fitness to Practise Committee, a Professional Conduct Committee or a Health Committee. Remediation completed before the hearing, dated and documented, is evidence you can put before the committee and the regulator.
The concerns this course speaks to
Billing and claims
Claims for appointments cancelled or not attended, up-coding, duplicate claims, eligibility assumed. Section 3 covers the principles of ethical billing, the errors that attract scrutiny, and what to do when you discover an error.
Fees and patient communication
Fees not explained before treatment, charges added without explanation, patients who felt pressured. Section 3 covers fees, charging policies and patient communication, and Section 9 transparent communication about fees day to day.
Conflicts of interest
Shares in a clinic or a pharmacy, reciprocal referrals, an interest in a product you recommend. Section 4 covers actual and perceived conflicts of interest, transparency as the primary safeguard, and managing conflicts in mixed public and private practice.
Gifts, incentives and sponsorship
Hospitality linked to a product, a device kept for personal use, a sponsored event. Section 5 covers what counts as a gift or incentive, what is permissible and what is high risk, sponsorship, and declining benefits safely.
Prescribing and referrals under financial influence
Repeated referrals to a service you own, a branded product prescribed where equivalents exist. Section 6 covers prescribing and referral decisions, disclosure, subtle financial pressures, and documentation as a protective measure.
Financial arrangements with a patient or a colleague
A financial arrangement can blur the professional relationship: a patient who feels unable to challenge a charge, a reciprocal referral arrangement with a colleague, referrals within a business partnership. Sections 1 and 4 cover the information imbalance between professional and patient, and the referral relationships with colleagues that create conflicts of interest.
Delegated billing
Claims submitted in your name by administrative staff or a third party. Section 3 covers delegation and oversight: you remain accountable for claims submitted in your name, and errors attributed to staff still reflect on your probity.
Patterns over time
Small inaccuracies repeated over months. Sections 2 and 3 explain why probity is assessed on patterns of behaviour rather than isolated incidents, and Section 9 covers self-audit and peer review.
Facing a complaint to your regulator or a fitness to practise inquiry? This course helps you remediate — and show it.
Buy this course — €100 (€70 with Bulk Buy 10)What the course covers
Ten sections and 83 lessons, with a reflective quiz closing each of the first nine and a post-course assessment at the end.
Introduction — Why Financial Integrity Matters in Irish Healthcare
Nine lessons
Professional Probity and Honesty in Financial Dealings
Nine lessons
Billing, Fees, Claims, and Financial Accuracy
Nine lessons
Conflicts of Interest and Transparency
Nine lessons
Gifts, Incentives, Sponsorship, and Industry Relationships
Nine lessons
Prescribing, Referrals, and Financial Influence
Nine lessons
Financial Concerns, Complaints, and Regulatory Investigations
Nine lessons
Reflection, Insight, and Remediation Following Financial Lapses
Nine lessons
Applying Financial Integrity to Daily Practice
Nine lessons
Conclusion and Key Takeaways
Two lessons, Conclusion and Key Takeaways, and the post-course assessment
Show every lesson title
- Section 01 · Introduction — Why Financial Integrity Matters in Irish Healthcare
- What Is Financial Integrity in Healthcare?; Why Financial Integrity Is Central to Public Trust; Financial Integrity as a Professional Requirement in Ireland; Common Areas Where Financial Integrity Concerns Arise; Financial Error vs Financial Integrity Concerns; Financial Integrity in Mixed Public–Private Practice; Financial Integrity as Part of Professional Identity; Consequences of Financial Misconduct; Why This Course Is Essential.
- Section 02 · Professional Probity and Honesty in Financial Dealings
- What Is Professional Probity in Financial Contexts?; Why Probity Is Treated So Seriously by Regulators; Honesty vs Technical Compliance; Common Probity Pitfalls in Everyday Practice; Transparency and Disclosure; Probity in Claims and Billing; Probity in Expense Claims and Allowances; Patterns, Not Isolated Incidents; Regulatory Expectations in Ireland.
- Section 03 · Billing, Fees, Claims, and Financial Accuracy
- Why Billing and Claims Are High-Risk Areas; Core Principles of Ethical Billing and Claims; Common Billing and Claim Errors That Attract Scrutiny; Billing in Public, Private, and Mixed Practice; Delegation, Administrative Support, and Oversight; Fees, Charging Policies, and Patient Communication; Discovering Errors: What To Do; Patterns, Cumulative Risk, and Audit Trails; Regulatory Expectations in Ireland.
- Section 04 · Conflicts of Interest and Transparency
- What Is a Conflict of Interest in Healthcare?; Why Conflicts of Interest Are Taken So Seriously; Common Financial Conflicts of Interest in Irish Practice; Perceived vs Actual Conflicts of Interest; Transparency: The Primary Safeguard; Managing Conflicts of Interest Appropriately; Conflicts of Interest in Mixed Public–Private Practice; Common Mistakes That Escalate Conflict Issues; Regulatory Expectations in Ireland.
- Section 05 · Gifts, Incentives, Sponsorship, and Industry Relationships
- Why Gifts and Incentives Are High-Risk Areas; What Counts as a Gift or Incentive?; Acceptability: What Is Permissible vs High Risk; Sponsorship and Funded Learning Events; Industry Relationships and Advisory Roles; Gifts, Incentives, and Prescribing or Referrals; Transparency and Disclosure; Managing and Declining Benefits Safely; Regulatory Expectations in Ireland.
- Section 06 · Prescribing, Referrals, and Financial Influence
- Why Prescribing and Referral Decisions Are High-Risk; Prescribing Decisions and Financial Influence; Referrals and Financial Gain; Mixed Public–Private Practice and Referral Integrity; Transparency and Disclosure in Prescribing and Referrals; Identifying and Managing Subtle Financial Pressures; Documentation as a Protective Measure; Patterns of Behaviour and Escalating Risk; Regulatory Expectations in Ireland.
- Section 07 · Financial Concerns, Complaints, and Regulatory Investigations
- How Financial Concerns Arise in Practice; What Regulators Examine in Financial Integrity Investigations; Employer Investigations and Parallel Regulatory Processes; How to Respond When a Financial Concern Is Raised; Audits, Reviews, and Information Requests; Writing Statements and Explanations About Financial Issues; Demonstrating Insight in Financial Integrity Cases; Remediation After Financial Concerns Are Identified; Regulatory Expectations in Ireland.
- Section 08 · Reflection, Insight, and Remediation Following Financial Lapses
- Why Reflection, Insight, and Remediation Are Decisive in Financial Cases; Reflection: Analysing the Financial Lapse Honestly and Specifically; Insight: Recognising Seriousness and Accepting Responsibility; Financial Lapses That Require Remediation; Remediation: Turning Learning Into Practical Change; Evidence: Demonstrating Improvement Credibly; Weak vs Strong Responses in Financial Investigations; Embedding Financial Integrity Learning Into Ongoing Practice; Regulatory Expectations in Ireland.
- Section 09 · Applying Financial Integrity to Daily Practice
- Adopting a “Probity-First” Mindset; Daily Habits for Accurate Billing and Claims; Transparent Communication About Fees and Charges; Managing Conflicts of Interest Day-to-Day; Delegation With Oversight; Handling Errors Promptly and Transparently; Routine Self-Audit and Peer Review; Managing Pressure and Avoiding Rationalisation; Aligning Daily Practice With Regulatory Expectations.
- Section 10 · Conclusion and Key Takeaways
- Conclusion; Key Takeaways.
How to respond to a financial complaint or fitness to practise inquiry
Whether it is read by an auditor, your employer, a preliminary committee or an inquiry committee, a response about money is read for honesty and for whether it could happen again. These are the four parts to set out, and what the course gives you for each.
In a financial case the sum matters less than what the response shows about integrity.
- What happenedThe lapse stated precisely: which claims, which fees, which interest, over what period.Section 8 sets out what an honest, specific reflection on a financial lapse includes.
- How it aroseA knowledge gap, an oversight, a delegation failure or pressure — explained without excuse.Section 7 covers writing statements and explanations about financial issues.
- Why it mattersIts effect on patients, public funds and trust, whatever the amount.Section 8 has a lesson on insight: recognising seriousness and accepting responsibility.
- What has changedRepayment, checks before submission, self-audit, independent review — with evidence.Section 8 covers remediation and the evidence of it — and this course is a dated item for your portfolio.
It was only a small amount describes the sum; it does not answer the concern about integrity.
Take advice from your indemnifier, your union or professional body, or a solicitor before you respond to anyone.
Facing a complaint to your regulator or a fitness to practise inquiry? This course helps you remediate — and show it.
Buy this course — €100 (€70 with Bulk Buy 10)How this course helps with a complaint or fitness to practise inquiry
Financial concerns appear in the grounds and the sanctions
Professional misconduct is a ground of complaint under the Medical Practitioners Act, the Nurses and Midwives Act, the Pharmacy Act and the Health and Social Care Professionals Act, and a ground for an inquiry under the Dentists Act. Contravening regulations under the Health (Pricing and Supply of Medical Goods) Act 2013 is also a ground under the Medical Practitioners Act and the Nurses and Midwives Act, and for an inquiry under the Dentists Act. NMBI lists fraud or criminal matters among its categories of alleged conduct (State of Complaints 2024), and the sanctions available include censure with a fine of up to €5,000 for doctors (MPA s.71) and €2,000 for nurses and midwives (NMA s.69). The course covers billing, fees and claims (Section 3), conflicts of interest (Section 4), gifts and industry relationships (Section 5), and prescribing and referrals (Section 6).
Insight and remediation in a financial case
NMBI’s Guidance on Sanctions lists “acknowledgement and early admission” and “whether the nurse or midwife has taken remedial action where appropriate” among mitigating factors, and the Medical Council’s Guidance on Sanctions says a doctor may “demonstrate insight by providing evidence of their understanding of the problem”. In the cases CORU concluded in 2022 to 2024, personal and professional conduct including dishonesty was a theme in 49% (trends report). Section 7 covers responding to a financial concern and demonstrating insight, and Section 8 remediation with evidence. For the stages from the first letter to the High Court, see the fitness to practise process in Ireland, explained.
Read the primary sources
- Medical Practitioners Act 2007, section 57 — grounds of complaint
- Nurses and Midwives Act 2011, section 55 — grounds of complaint
- Dentists Act 1985, section 38 — inquiries
- State of Complaints 2024 — NMBI
- Medical Practitioners Act 2007, section 71 — sanctions
- Nurses and Midwives Act 2011, section 69 — sanctions
- Guidance on Sanctions — Nursing and Midwifery Board of Ireland
- Guidance on Sanctions Imposed by the Medical Council (28 May 2024)
- CORU fitness to practise trends report (2022 to 2024)
Who wrote it

Dr Shehzad Iqbal
Course author and facilitator, Healthcare Ethics Ireland
Dr Iqbal wrote this course. He combines clinical practice with a formal postgraduate qualification in healthcare law and ethics, and has worked with registrants across the regulated health professions, online and face to face, since 2020.
He founded Probity & Ethics in the United Kingdom in 2020 and Healthcare Ethics Courses, which issues the certificates, in 2025. More about us.
MBBS · MRCS · MRCGP · Postgraduate Certificate in Healthcare Law and Ethics, University of Dundee
Written and reviewed by Dr Shehzad Iqbal. Last reviewed .
In short
Financial Integrity for Healthcare Professionals is a two-hour, self-paced remediation course for healthcare professionals in Ireland — registered with the Medical Council, NMBI, the Dental Council, the Pharmaceutical Society of Ireland or CORU — who face a complaint, an audit or a fitness to practise inquiry about billing, claims, fees, expenses or a financial interest. It covers why financial integrity is central to public trust, including in mixed public and private practice; probity and honesty in financial dealings, claims, expenses and allowances; billing, fees, claims, delegation and audit trails; conflicts of interest and transparency; gifts, incentives, sponsorship and industry relationships; prescribing, referrals and financial influence; financial concerns, complaints, audits and investigations, and writing statements about them; reflection, insight and remediation after a financial lapse; and applying financial integrity day to day. Ten sections, the first nine closing with a reflective quiz, a post-course assessment, and a dated certificate from Healthcare Ethics Courses. It is remediation and dated evidence of it; it decides no complaint, and it is not a substitute for advice from your indemnifier, your union or professional body, or a solicitor.
What financial integrity means for a registered professional
Financial integrity means acting with honesty, transparency and ethical judgement in every financial aspect of professional practice. The course defines it that way (Section 1) and applies it to billing and fees, claims to public or private payers, salaries, allowances and expenses, prescribing or referral decisions with financial implications, gifts and sponsorship, and ownership interests. It is not about maximising income, and it is not justified by everyone does it.
The course separates a financial error — a misunderstanding or an administrative mistake, corrected promptly — from a financial integrity concern, where behaviour is careless, reckless, repeated or dishonest, or a known error is left uncorrected (Section 1). It explains why repeated errors without insight may come to be treated as dishonesty, and why the response after a lapse carries so much weight (Sections 2 and 8).
In a written response, state the lapse precisely, explain how it arose without excuse, say why it matters to trust, and show what has changed: repayment, checks and audit results.
What these words mean
The three terms that decide where a complaint goes, and the words the course is built on.
- Preliminary Proceedings Committee
- The committee of the Medical Council, NMBI, the PSI and CORU that looks at a complaint before any inquiry: it may take no further action, suggest mediation, conclude the matter with an undertaking or a consent where its Act allows, or refer the complaint to an inquiry. At the Dental Council, the Fitness to Practise Committee considers whether there is a prima facie case.
- Fitness to practise inquiry
- The hearing stage: before the Fitness to Practise Committee at the Medical Council, NMBI and the Dental Council, and before the Professional Conduct Committee or the Health Committee at the PSI and CORU. Any sanction heavier than an advice, admonishment or censure takes effect only when the High Court confirms it.
- Professional misconduct
- A ground of complaint under the Medical Practitioners, Nurses and Midwives, Pharmacy and Health and Social Care Professionals Acts, and a ground for an application for an inquiry under the Dentists Act. The Dental Council describes it as a serious falling short in the standards expected of a dentist; the PSI as behaviour that goes against its Code of Conduct for registered pharmacists; CORU as any act, omission or pattern of conduct that breaches the Code.
Conflicts of interest, up-coding and the other terms the course uses
- Financial integrity
- Honesty, transparency and ethical judgement in every financial aspect of professional practice.
- Probity
- Honesty, integrity and trustworthiness; in financial matters, information that is accurate, truthful and able to withstand independent scrutiny.
- Conflict of interest
- A personal, financial or business interest that could reasonably be seen to influence professional judgement. The course treats perceived conflicts as a concern alongside actual ones.
- Up-coding
- Claiming a higher-value code than the service justifies, or inflating the length or complexity of a consultation.
- Duplicate claim
- Submitting the same claim twice, or claiming across different funding streams for the same service.
- Mixed public and private practice
- Working across the public and private systems; the course covers double charging, prioritising private patients, and blurring public duties with private benefit.
- Self-audit
- A professional’s own scheduled review of claims, expenses and disclosures, to find and correct discrepancies early.
- Repayment
- Returning money from incorrect claims; the course treats repayment with written confirmation as part of strong remediation.
- Remediation
- Concrete, targeted measures that prevent recurrence and restore confidence: relevant, proportionate, sustained and verifiable.
The Acts a complaint is made and decided under
Ireland’s five health regulators each work under their own Act, all five amended by the Regulated Professions (Health and Social Care) (Amendment) Act 2020. These are the sections that say who may complain, on what grounds, and who looks at the complaint first.
Medical Council — Medical Practitioners Act 2007, section 57
A person, including the Council, may complain to the chief executive officer. The grounds include professional misconduct, poor professional performance, a relevant medical disability, and a failure to comply with a condition, an undertaking or a consent. The chief executive officer looks at the complaint first, an Authorised Officer may gather the facts, and the Preliminary Proceedings Committee decides whether there is enough cause to take further action. Read it.
For this course: For a doctor, a billing, referral or prescribing concern is answered with honesty and insight; Section 6 covers prescribing and referrals under financial influence.
NMBI — Nurses and Midwives Act 2011, section 55
A person, including the Board, may complain to the chief executive officer. The grounds include professional misconduct, poor professional performance, non-compliance with a code of professional conduct, a relevant medical disability, and an irregularity in relation to the custody, prescription or supply of a controlled drug. A Preliminary Proceedings Committee, assisted by a case officer, may refer a complaint to the Fitness to Practise Committee for a sworn oral inquiry. Read it.
For this course: Section 2 covers probity in expense claims and allowances, and Section 7 writing statements about financial issues.
Dental Council — Dentists Act 1985, section 38
The Council or any person may apply to the Fitness to Practise Committee for an inquiry, on grounds that include alleged professional misconduct and alleged unfitness to practise by reason of physical or mental disability. The Fitness to Practise Committee considers whether there is a prima facie case, and if there is, it holds the inquiry. Read it.
For this course: Section 3 covers fees, charging policies and patient communication, and billing in public, private and mixed practice.
Pharmaceutical Society of Ireland — Pharmacy Act 2007, section 35
A complaint may be made in writing by or on behalf of any person, or by the registrar. The grounds include professional misconduct, poor professional performance, the effect on practice of a physical or mental ailment, emotional disturbance, or alcohol or drug addiction, and a failure to comply with a condition or an undertaking. The PSI separates a concern from a statutory complaint, which is for issues of a serious nature; its Preliminary Proceedings Committee may refer a complaint to a committee of inquiry or to mediation. Read it.
For this course: Section 4 covers conflicts of interest in pharmacies and products, and Section 5 gifts and incentives linked to prescribing or referrals.
CORU — Health and Social Care Professionals Act 2005, section 52
A complaint may be made to the Council by or on behalf of any person, or by a registration board. The grounds include professional misconduct, which CORU describes as any act, omission or pattern of conduct that breaches the Code, and poor professional performance. The Preliminary Proceedings Committee screens out complaints that are trivial, vexatious, without substance or made in bad faith; the Professional Conduct Committee deals with conduct or competence, and the Health Committee with whether a registrant’s health is affecting their ability to practise. Read it.
For this course: Section 7 covers audits, information requests and writing statements about financial issues, and Section 8 remediation after a financial lapse.
Also engaged: Sanctions — advice, admonishment or censure, conditions, suspension and cancellation (erasure under the Dentists Act): Medical Practitioners Act s.71, Nurses and Midwives Act s.69, Dentists Act ss.39 to 41, Pharmacy Act s.48, Health and Social Care Professionals Act s.66 · High Court confirmation — the heavier sanctions take effect only when the High Court confirms them; an advice, admonishment or censure on confirmation or once the appeal window of 21 or 30 days passes without an appeal · The 2020 Act — the Regulated Professions (Health and Social Care) (Amendment) Act 2020, which amended all five Acts in stages from 2021 to 2025.
What happens after a complaint reaches an Irish regulator
Each regulator has its own Act and its own names for the stages, and your letter tells you which stage you are at. At each of them the same three things are worth showing in writing: that you see what went wrong, that you understand it against your regulator’s code, and what you have changed, with dated evidence.
The complaint and the grounds
Anyone may complain, including the regulator itself. Under the Medical Practitioners Act and the Nurses and Midwives Act the complaint goes to the chief executive officer; under the Pharmacy Act it may be made by or on behalf of any person or by the registrar; under the Health and Social Care Professionals Act by or on behalf of any person or by a registration board. Under the Dentists Act the Council or any person applies to the Fitness to Practise Committee for an inquiry. Professional misconduct is a ground of complaint under the four other Acts and, under the Dentists Act, a ground for an application for an inquiry.
The preliminary stage
The Medical Council, NMBI, the PSI and CORU each have a Preliminary Proceedings Committee. At the Medical Council the chief executive officer looks at a complaint first and may assign an Authorised Officer, and the committee decides whether there is enough cause to take further action. At NMBI the committee may refer a complaint to the Fitness to Practise Committee for a sworn oral inquiry, or suggest mediation or informal resolution; at the PSI it may refer a complaint to a committee of inquiry or to mediation; at CORU it screens out complaints that are trivial, vexatious, without substance or made in bad faith. At the Dental Council, the Fitness to Practise Committee considers whether there is a prima facie case.
Undertakings, consents and mediation
A complaint can be concluded by agreement in some cases. At the Medical Council’s preliminary stage a doctor may be asked to undertake not to repeat the conduct, or to consent to censure (2025 procedures). At NMBI in 2024, 12 undertakings or consents concluded matters at the preliminary stage and the Fitness to Practise Committee recommended 32 (State of Complaints 2024). Undertakings were the largest single Committee of Inquiry outcome in the cases CORU concluded in 2022 to 2024: 13, against 7 censures (trends report). In 2024 the Dental Council accepted undertakings from a dentist instead of making a High Court application (Annual Report 2024). Mediation at NMBI and CORU needs the consent of both sides.
The inquiry
The inquiry committee is the Fitness to Practise Committee at the Medical Council, NMBI and the Dental Council, and the Professional Conduct Committee or the Health Committee at the PSI and CORU. At NMBI allegations against a nurse or midwife must be proven beyond reasonable doubt. Medical Council inquiries are held in public unless the Council decides on a hearing in private or part private (Medical Council); CORU says its Professional Conduct Committee hearings are normally held in public and its Health Committee hearings normally in private.
The sanction and the High Court
Sanctions run from advice, admonishment or censure (admonishment or censure at the PSI and CORU) through conditions and suspension to cancellation, called erasure under the Dentists Act (MPA s.71, NMA s.69, Dentists Act s.39, Pharmacy Act s.48, HSCP Act s.66). The heavier sanctions take effect only when the High Court confirms them; an advice, admonishment or censure takes effect on confirmation or once the appeal window passes without an appeal: 21 days for doctors, nurses, midwives and dentists, 30 days for pharmacists and CORU registrants (MPA s.74, NMA s.72, Dentists Act s.41, Pharmacy Act s.50, HSCP Act s.68).
Interim measures and your first reply
Separately, the Medical Council says interim suspension is possible under section 60 of the Medical Practitioners Act 2007; where there is a serious and immediate risk, the PSI’s Council can seek suspension from the High Court; and the Dental Council may apply to the High Court for suspension under section 44 of the Dentists Act. None of the five regulators publishes a fixed deadline for a first reply: the Medical Council gives not less than two weeks to respond to an Investigation Report, and NMBI says you may request an extension of time. Take advice before you reply.
Facing a complaint to your regulator or a fitness to practise inquiry? This course helps you remediate — and show it.
Buy this course — €100 (€70 with Bulk Buy 10)Courses with the Ethics and Professionalism pair written to your own regulator’s code — for doctors, nurses and midwives, dentists, pharmacists and all other healthcare professionals, or every course →
Frequently asked questions
It was a billing error, not dishonesty. How will it be judged?
The course explains that a financial error corrected promptly is viewed differently from a pattern of inaccuracies left unchecked, and that the assessment turns on honesty and openness, willingness to correct and insight. Whether you knew or should have known, whether you benefited, and whether you corrected it voluntarily all count (Sections 1 and 7).
My administrative staff submitted the claims. Am I responsible?
The course is clear that you remain accountable for claims submitted in your name, and that I did not submit it myself is not a defence. Section 3 covers delegation and oversight — clear instructions, regular review, spot-checks — and Section 9 delegation with oversight day to day.
Should I repay the money?
The course treats prompt correction, and repayment where appropriate, as part of the professional response, and repayment with written confirmation as part of strong remediation (Sections 3 and 8). Ask your adviser how and when to repay, and keep a record of it.
I did not think my interest needed declaring. What now?
The course explains that a conflict does not require wrongdoing, that perceived conflicts matter as well as actual ones, and that late disclosure is viewed more critically than early transparency. Section 4 covers declaring and managing conflicts of interest, and Section 6 disclosure in prescribing and referrals.
Should I take advice before I respond?
Yes — before anything is written to the regulator, a committee or your employer. Ask your indemnifier, your union or professional body, or a solicitor to read your response before it is sent, and keep a copy of everything you send. Nothing on this page is legal advice.
Can this course be used as evidence of remediation?
It can be part of the evidence, but no course decides a complaint. It gives you a dated certificate of 2 CPD hours. Section 8 covers the evidence that sits beside it: CPD certificates with reflective summaries, audit results showing improved accuracy, updated billing protocols or checklists, and supervisor or mentor attestations.
How long does it take, and how long do I have access?
The course is 2 CPD hours, self-paced, with access for twelve months from purchase. The certificate is issued on completion, dated, with the course title and the CPD hours. Whether the hours count towards your own CPD requirement is for your regulator or scheme to say: doctors must undertake a minimum of 50 hours in each scheme year, and CORU registrants must achieve 30 CPD credits in every 12-month period.
Can I get a certificate with a later date?
No. The certificate records the date you completed the course, and that date does not change. If your regulator, an inquiry committee or an employer asks for recent evidence, you buy the course again: half price within twelve months of your original purchase, the full €100 after that.
Will anyone be told that I am taking the course?
No. Nobody is told you are enrolled. We do not share participant details with any regulator, an employer, a union or an indemnifier; the certificate reaches them only if you attach it to your own response.
Courses that work alongside this one
A financial concern is a probity concern, and can involve prescribing and records too. These are the courses that pair with this one.
Probity and Honesty for Healthcare Professionals
Integrity, transparency and fairness, dishonesty set against clinical error, probity in documentation and billing, and weak and strong responses to a probity concern.
Documentation for Healthcare Professionals
Good clinical documentation, consent and capacity, handover records, digital records and data protection, and records during a complaint.
Prescribing Guidance and Standards for Healthcare Professionals
Scope of practice, high-risk medicines and prescribing errors, self-prescribing and prescribing for people close to you, and prescribing records.
Professional Ethics Course
Probity, boundaries and conflicts of interest, digital professionalism, weak and strong demonstrations of professional ethics, and ethical portfolios.
Ethical Boundaries with Patients and Colleagues
Boundaries with patients (emotional, sexual, financial, digital) and with colleagues (hierarchy, respect, bullying, conflicts of interest), and weak and strong responses.
Insight for Fitness to Practise
What insight is, how the five regulators frame it, weak and strong demonstrations of insight, and how insight is shown in a portfolio and at a hearing.
Remediation for Fitness to Practise
What a regulator looks for in remediation, what a remediation portfolio contains, case studies across five professions, and remediation at a hearing.
Financial Integrity for Healthcare Professionals
This course. Billing, fees and claims, conflicts of interest, gifts and sponsorship, prescribing and referrals, and remediation after a financial concern.
Start today, finish at your own pace
Immediate access on purchase. Twelve months' access, a dated certificate on completion, and 2 CPD hours issued by Healthcare Ethics Courses.